

{{item.videoDuration}}
{{item.title}}

{{item.videoDuration}}
Health is increasingly part of everyday life, shaping meals, commutes, shopping, pharmacy visits, wearables, and AI-driven advice. PwC’s Voice of the Consumer 2026 survey of 1,003 consumers in Ireland shows that people are regularly buying, tracking, and adjusting for their wellbeing, so health is more continuous, personalised, service-led, consumer-driven, and built into daily routines. According to our survey, consumers are already focused on living longer, reducing stress, improving sleep, managing weight, pursuing personal growth, and feeling more confident in their appearance.
Consumer demand for wellness is broadening beyond traditional health products and into a wider range of everyday goods, services, and digital experiences. Our Voice of the Consumer Survey 2026 shows that Irish consumers are already making discretionary purchases across a broad wellness landscape, including vitamins and supplements, speciality health food and beverages, beauty treatments, health screening, fitness services, wearable devices, sleep aids, health and fitness apps, and mental health support.
Looking ahead, consumption patterns also point to continued engagement with categories linked to healthier living, including fresh produce, supplements, dairy and meat alternatives, or plant-based protein. This suggests that wellness is increasingly shaping both discretionary spending and routine grocery choices, as consumers look for products and services that support their personal health and wellbeing goals.
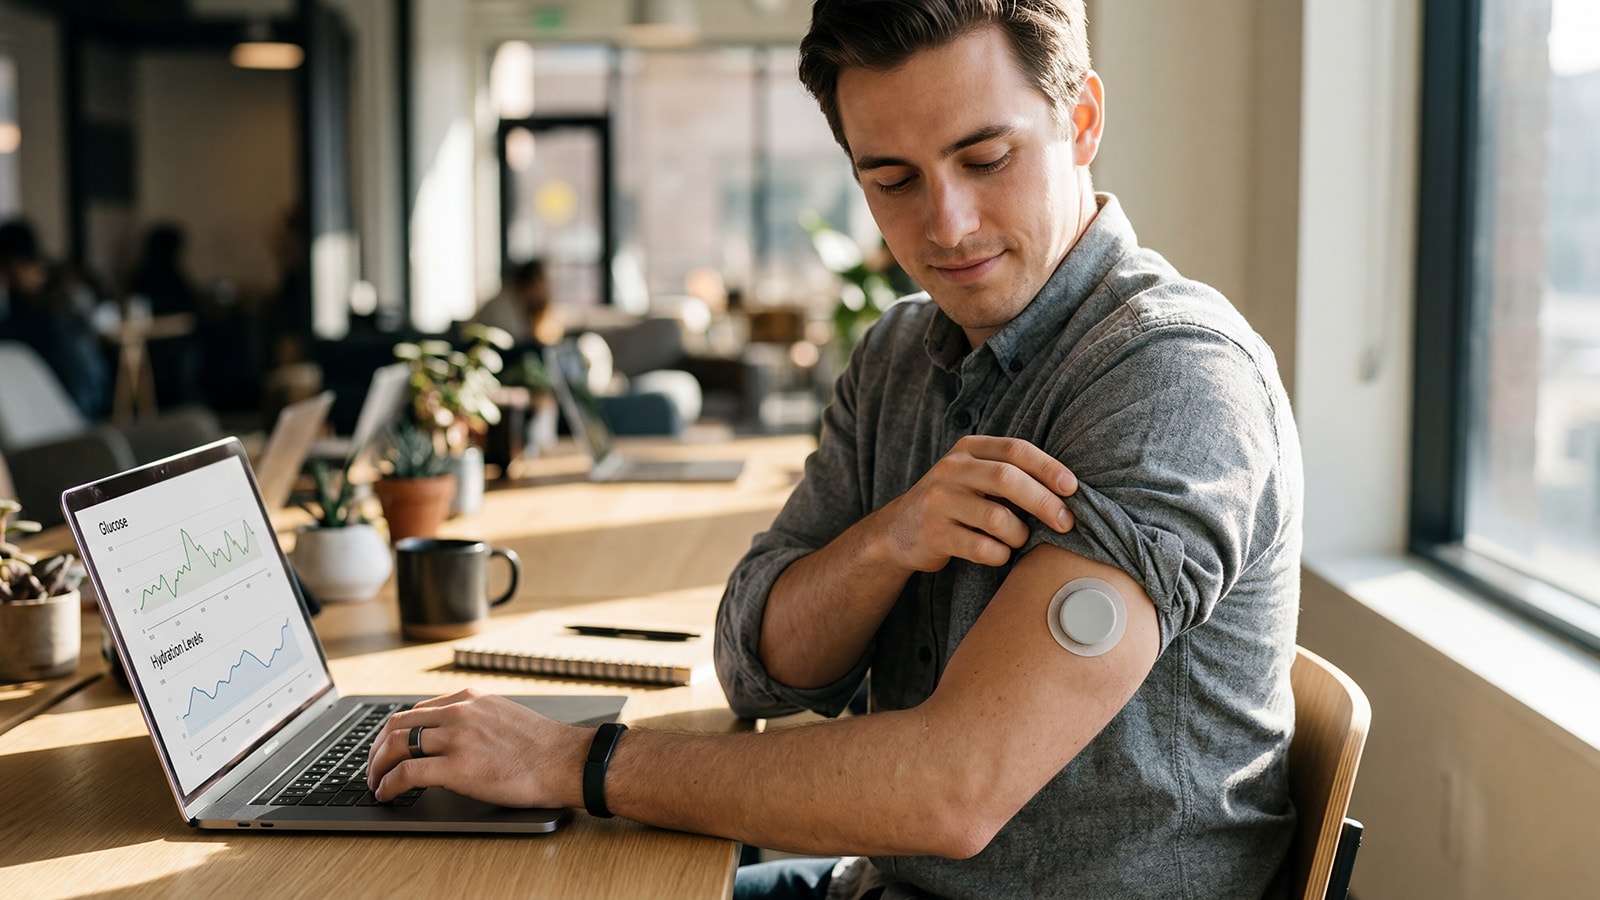
This widening definition of wellness is closely connected to consumers’ increasing reliance on technology, and particularly the emergence of AI-enabled health tools. Younger generations are more comfortable allowing AI to support health and wellness tasks such as nutritional guidance, personalised fitness planning, health data analysis, and recommendations based on individual needs. Wearables, apps, and digital platforms are therefore becoming important routes through which consumers track, interpret and act on their wellness goals.
For consumer and retail businesses, this means wellness can no longer be treated as a standalone category. It’s becoming embedded across shopping missions, product choices, service expectations, and digital engagement. The opportunity lies in connecting credible health-led propositions with convenient, personalised, and technology-enabled experiences that help consumers make better-informed decisions.
As Irish consumers continue to prioritise health and wellness, the opportunity for consumer and retail businesses is significant. However, growth will depend on how effectively brands and retailers can make healthier choices feel accessible, affordable, and easy to understand.
Our Voice of the Consumer Survey 2026 shows that consumers remain highly practical when choosing products and services to support their health goals. Value for money and cost are the most important considerations, underlining that wellbeing propositions must prove their worth in a market where household budgets remain under pressure. Consumers may be motivated to improve their health, but they still need confidence that products and services offer tangible value.
Beyond price, convenience is a key factor. Health-focused products and services are more likely to succeed when they’re simple to use, easy to access, and capable of fitting into consumers’ everyday routines. This presents a clear challenge for brands: wellness must not feel complicated, time-consuming, or difficult to adopt.
Clear information is also essential. As the health and wellness market becomes more crowded, consumers need to understand what a product or service does, how it works, and how it supports their individual goals. Brands that communicate benefits simply and transparently will be better placed to build trust and encourage purchase.
Personalisation is another important part of the picture. Consumers increasingly value products and services that feel relevant to their own needs, lifestyles and goals. For retailers and consumer brands, the opportunity lies in combining affordability with simplicity, clarity, and relevance.
Put simply, health and wellness growth will not be driven by aspiration alone. To convert consumer interest into sustained demand, businesses must remove friction from the buying journey and make health easier to buy.
Digital tools are becoming an increasingly important entry point for consumers seeking to manage their health and wellness, with younger generations showing greater openness to AI-enabled support. Our Voice of the Consumer Survey 2026 indicates that consumers are most comfortable using AI for practical, lifestyle-oriented health tasks – particularly where the application is easy to understand and linked to everyday wellbeing goals.
Acceptance is highest among younger consumers for AI-enabled nutritional guidance, including meal planning, customised grocery lists, and nutrition coaching, as well as personalised fitness and wellness planning. These use cases suggest that consumers are more willing to engage with AI where it supports preventative health, convenience, and personal goal-setting rather than replacing clinical judgement.
The survey also shows emerging comfort with AI analysing health data to identify potential issues such as poor sleep or high stress, and with tools that provide an initial medical review or recommendations based on symptoms. However, comfort levels are lower for more complex or sensitive applications, such as advanced medical diagnosis, treatment planning, or handling payment, credit card, and insurance information. This points to the importance of trust, transparency, and appropriate safeguards as digital health propositions develop.
Generational differences are also clear. Younger consumers are consistently more comfortable than older consumers with allowing AI to perform health and wellness tasks, with the largest differences seen across areas such as predicting health issues, providing diagnosis-related recommendations, and supporting personalised lifestyle interventions. By contrast, a much higher proportion of older consumers selected “none of the above”, indicating lower readiness to adopt AI-enabled health tools.
For consumer and retail businesses, the implication is that the first health interaction may increasingly begin through a digital channel, app, platform, or AI-enabled service. Growth opportunities will depend on building solutions that are useful, secure, and easy to navigate while clearly explaining how data is used and where human expertise remains central. Brands that combine digital convenience with trust and credibility will be better positioned to support consumers’ evolving health and wellness expectations.
GLP-1 medications are emerging as an important indicator of how health-related consumption may evolve. In Ireland, current use is 6% – below the global average – with most Irish consumers surveyed saying they have never taken a GLP-1 prescription medication for type-two diabetes and/or weight loss. However, a smaller group of Irish respondents are either currently taking these medications or have taken them in the past, indicating that GLP-1s are already part of the consumer health landscape.
Globally, GLP-1 use has increased significantly over the past year, with current usage doubling compared with the previous survey period. While year-on-year comparisons should be treated with care due to changes in question wording, the findings point to rising consumer exposure to these treatments and their potential to influence adjacent categories, including food, wellness, fitness, and lifestyle services.
The behavioural data suggests that GLP-1 users are not only changing what they eat but also engaging more broadly with health and wellbeing. Among current users surveyed, reported changes include greater attention to nutrition and food labels, increased exercise, and higher spending on health and wellness-related products. Some users also report changes in how much they socialise, their spending on personal style and appearance, the amount they travel, and how often they eat out.
The findings indicate that GLP-1s may act as a catalyst for wider lifestyle adjustments. Globally, GLP-1 users are more likely than non-users to monitor fibre, protein, and calorie intake, and to engage with sleep tracking, counselling services, community wellness activities, and nutrition or dietary planning.
For Irish consumer and retail businesses, the relevance isn’t limited to the medication itself. GLP-1 adoption illustrates how a health intervention can reshape demand across multiple categories. As awareness and usage develop, businesses will need to monitor how consumer needs change around portion size, nutrition, labelling, high-protein and high-fibre products, fitness, wellbeing services, and personalised support. The opportunity will be strongest for brands that respond with credible, clearly communicated, and health-focused propositions.
Design products around health occasions: Build propositions for moments such as sleep, hydration, and recovery with products tailored to outcomes including mood, longevity, metabolic support, weight management, and gut health.
Support consumers with simple guidance: Present products in clear prompts, subscriptions, or nutrition plans that help consumers understand what to consume and how it supports their goals, while maintaining convenience, affordability, and great taste.
Design for health-focused home environments: Treat the home as a space that supports sleep, recovery, appearance, and safety through products such as supplements and smart environments.
Use data to provide practical guidance: Apply diagnostics, AI analysis, and tracking data to deliver recommendations that help consumers improve routines while keeping solutions simple and accessible to integrate into daily life.
Organise health around consumer goals: Connect food, supplements, diagnostics, devices, pharmacy advice, and services around needs such as sleep, stress, weight, energy, and recovery rather than traditional product categories.
Build trust through expert guidance and value: Use pharmacy relationships, clear value exchange, and personalised recommendations to help consumers navigate health choices safely, while encouraging responsible data sharing and engagement across channels.
Use everyday health concerns as entry points: Engage consumers before formal care through needs related to sleep, stress, weight, prevention, adherence, remote monitoring, and digital triage, supported by diagnostics, coaching, and personalised care pathways.
Design services for carers and connected care: Support family members and carers choosing monitoring tools, care navigation, and at-home support for older relatives, while extending provider relationships beyond clinical settings through pharmacies, digital channels, and community-based care.
Design around the full patient pathway: Build support across awareness, diagnosis, treatment initiation, adherence, lifestyle support, and outcomes tracking, helping patients manage the behaviours that influence results before, during, and after therapy.
Create partnerships that extend therapy support: Work with providers, pharmacies, diagnostics, digital health, data platforms, and consumer health players to combine medication with monitoring, coaching, education, and personalised support beyond the product itself.
If you’re looking to navigate a changing landscape, our team can help you turn insight into action. From emerging trends and shifting behaviours to new challenges and opportunities, we provide tailored guidance to support your goals. Let’s explore how you can make confident decisions, adapt effectively, and stay ahead in a market that continues to evolve. Contact us today.



Menu